QUESTION PAPER
2026 BOARD EXAM
CBSE Class 12 Commerce Accountancy Board Paper 2026 — Set 4
2026
Accountancy
Class 12 Commerce
CBSE EXAMINATION PAPER-2026
ACCOUNTANCY
(Solved)
General Instructions :
Read the following instructions carefully and follow them :
- This question paper contains 57 questions. All questions are compulsory.
- This question paper is divided into 4 sections.
- Section A – questions number 1 to 33 are multiple choice questions
- Section B – questions number 34 to 43 are short answer
- Section C – questions number 44 to 49 are long answer type i
- Section D – questions number 50 to 57 are long answer type ii
- There is no overall choice given in the question paper. However, an internal choice has been provided in few questions.
- Use of calculator is NOT allowed.
Section A
Reena and Teena were partners in a firm sharing profits and losses in the ratio of 2 : 1. Teena withdrew₹20,000 at the beginning of each month during the year ended 31st March, 2025. Interest on drawings was to be charged @ 6% per annum. Interest on Teena’s drawings for the year ended 31st March, 2025 will be :
Rohan and Sohan were partners in a firm sharing profits and losses equally. Rohan withdrew Rs 15,000 at the beginning of each quarter during the year ended 31 March, 2025. Interest on Rohan’s drawings will be calculated for an average period of :
P, Q and R were partners in a firm sharing profits and losses in the ratioof 6 : 5 : 4. They admitted S as a new partner for 1/ 8 th share in the profits of the firm. It was agreed that Q would retain his original share. The sacrificing ratio of P and R will be :
Ravi, Sunil and Amit were partners in a firm sharing profits and losses in the ratio of 4 : 3 : 5. On 1st April, 2025, Ravi retired. Sunil and Amit decided to share future profits in the ratio of 2 : 3. After all adjustments with respect to general reserve, goodwill and revaluation, balances in the capital accounts of Ravi, Sunil and Amit stood at ₹ 3,00,000; ₹2,40,000 and ₹ 3,60,000 respectively. It was decided that the amount payable to Ravi will be brought by Sunil and Amit in such a way so as to make their capitals proportionate to their new profit sharing ratio. The amount brought in by Sunil and Amit will be :
5,000 shares of ₹ 20 each were forfeited for non-payment of second and final call of ₹ 4 per share. The minimum amount that the company must collect at the time of reissue of these shares will be :
Ravi, Sohan and Neena were partners in a firm sharing profits and losses in the ratio of 5 : 3 : 2. On 1st April 2025, Sohan retired and his share was taken up by Ravi and Neena in the ratio of 2 : 1. The new profit sharing ratio between Ravi and Neena will be :
Kunal, Raj and Leela were partners in a firm sharing profits and losses in the ratio of 4 : 3 : 2. On 1st April, 2025, Kunal retired. Raj and Leela decided to share profits in the future in the ratio of 5 : 3. The gaining ratio between Raj and Leela will be :
Ravi, Nisha and Priya were partners in a firm sharing profits and losses in the ratio of 4 : 3 : 1. Ravi retired and the balance in his Capital Account after making necessary adjustments on account of reserves and revaluation of assets and re-assessment of liabilities was ₹ 2,40,000. Nisha and Priya agreed to pay him ₹ 2,70,000 in full settlement of his claim. The value of goodwill of the firm was :
Ankur and Angad were partners in a firm sharing profits and losses in the ratio of 8 : 7. On 1st July, 2024, Angad advanced a loan of ₹ 8,00,000 to the firm. There is no partnership deed. Angad demands interest on loan @ 10% p.a. On 31st March, 2025, the amount of interest on loan due to Angad will be :
__________ debentures refer to those debentures where a charge is created on the assets of the company for the purpose of payment in case of default.
As per the provisions of Companies Act, 2013, the amount received as Securities Premium cannot be utilised to :
A business earned an average profit of ₹ 2,00,000 during the last few years. The value of net assets of the business is ₹ 17,00,000 and the normal rate of return in a similar business is 10%. The value of goodwill of the business by capitalisation of super-profits method will be :
Asha, Manan and Niyati were partners in a firm sharing profits and losses in the ratio of 3 : 2 : 1. With effect from 1st April, 2025, they agreed to share profits and losses equally. Due to change in the profit-sharing ratio, Asha’s gain or sacrifice will be
Dinesh, Siddharth and Naina were partners in a firm sharing profits and losses in the ratio of 5 : 3 : 2. On 31st March, 2025, they decided to dissolve the firm. On this date, the firm had debtors amounting to ₹ 2,10,000 and provision for doubtful debts of ₹ 20,000. On dissolution, debtors of ₹ 10,000 proved bad and the remaining debtors realised 90%. Amount realised from debtors will be :
Amik Ltd. issued 70,000, 9% Debentures of ₹ 100 each at a premium of 5%, redeemable at a premium of 10%. ‘Loss on Issue of Debentures Account’ will be debited in the books of Amik Ltd. by :
A portion of the uncalled capital reserved by a company to be called only in the event of winding up of the company is called :
White Ltd. purchased Plant and Machinery worth ₹ 3,96,000 from The purchase consideration was paid by of 9% Debentures of ₹ 100 each at 10% discount. The number of debentures issued were :
Statement I: Quick Credit Ltd., a finance company, paid interest on borrowings amounting to ₹80,000. This will be shown as cash outflow from operating activities in its Cash Flow Statement. Statement II : Royal Foods Ltd., a non-financial enterprise, paid dividends amounting to ₹ 2,30,000. It will be shown as cash outflow from operating activities in its Cash Flow Statement.
The following information was obtained about the cash flows of XYZ Ltd. for the year ended 31st March, 2025 :
Cash inflows from operating activities ₹ 28,000; cash used in investing activities ₹ 32,000 the and cash inflows from financing activiting ₹ 5000 . If the opening balance of cash and equivalents on 1st April, 2024 was ₹ 25,000, the closing balance of cash and cash equivalents on 31st March, 2025 will be
The Debt-Equity Ratio of a company is 2 : 1. Which of the following transactions will increase the Debt-Equity Ratio ?
Which of the following statements are correct ? (I). A low current ratio endangers the business and puts it at risk of facing a situation, where it will not be able to pay its short-term debts on time.
II Trade payables turnover ratio expresses the relationship between net credit sales and average trade payables.
III Operating profit ratio plus Gross profit ratio = 100.
IV Inventory turnover ratio determines the number of times inventory is converted into revenue from operations during the accounting period under consideration.
Fixed Asset Accounting sub-system generates information about :
A column chart can be changed to a pie chart because : I Only one data series is used to plot it. II The plotted data values are positive. III The data values are not equal to zero also. IV More than seven categories of data can be represented.
It is a widely accepted security control. It uses binary encoding format of storage to offer access to database. It is known as:
A1 : E2 refers to :
Section B
What is a ‘Radar Chart’ ? What purpose does it serve ?
What are the three categories in which entries can be classified while making voucher entry ?
Classify the following items under major heads and subheads (if any) in the Balance Sheet of the company as per Schedule III, Part I of the Companies Act, 2013 :
(a) Interest Accrued on Investments
(b)Calls-in-Advance
(c)Mortgage Loans
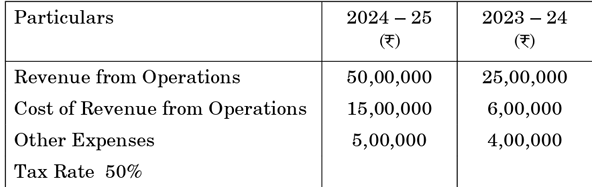
From the following information, prepare a Comparative Statement of Profit and Loss of AX Ltd. for the year ended 31 March, 2025 :
Aarav, Karan and Meera were partners in a firm sharing profits and losses equally. On 31 March, 2023, Karan retired. On the date of his retirement, Rs. 1,80,000 became due to him. Aarav and Meera agreed to pay Karan in two equal yearly instalments plus interest @ 12% p.a. on unpaid balance, starting from 31st March, 2024. The firm closes its books on 31st March every year. Prepare Karan’s loan account till it is fully paid.
Rohit, Ashish and Sameer entered into a partnership on1st october 2024 with capitals of Rs 12,00,000; Rs 6,00,000 and Rs. 6,00,000 respectively. They decided to share the profits and losses in the ratio of 3 : 1 : 1. Partners were entitled to interest on capital @ 5% per annum as per the provisions of the partnership deed.
Sameer was given a guarantee that his share of profit, after charging interest on capital, will not be less than Rs 1,50,000 per annum. Any deficiency arising on that account shall be met by Rohit. The profit for the year ended 31 March, 2025 amounted to Rs. 5,60,000. Prepare Profit and Loss Appropriation Account for the year ended 31st March, 2025.
Tara, Dev and Ishaan were partners in a firm sharing profits and losses in the ratio of 4 : 3 : 1. The partnership deed provided for charging interest on drawings @ 10% p.a. The drawings of Tara, Dev and Ishaan during the year ending 31st March, 2025 amounted to Rs. 30,000; Rs. 18,000 and Rs 12,000 respectively. After the final was accounts were prepared, it was discovered that interest on drawings not adjusting journal taken into to consideration. Give necessary adjusting journal entry to correct the omission. Show your workings clearly.
Sanjana and Mehul were partners in a firm sharing profits and losses in the ration in 4;1. From 1st April, 2025, they decided to share future profits and losses in the ratio of 5 : 3. On this date, their balance sheet showed a balance of Rs. 40,000 in General Reserve Account and a debit balance of and Rs. 1,80,000 in the Profit and Loss Account. The partners decided to distribute the General Reserve, but decided not to disturb the Profit Loss reconstituted firm. Pass Account, which will continue in the books of the necessary journal entries for the above transactions on the reconstitution of the firm. Show your workings clearly.
Century Ltd. forfeited 5,000 shares of Rs. 100 each issued at 40% premium for non-payment of allotment money of Rs. 35 per share and call yet of Rs. 50 per share (including premium Rs. 25). The second and final call of Rs 40 per share (including premium Rs 15) has not been called. Out of these, 3,000 shares were reissued as fully paid-up for Rs. 90 per share. Pass necessary journal entries for forfeiture and reissue of forfeited shares in the books of Century Ltd.
Almond Ltd. purchased a running business of Cashew Ltd. comprising of land and building Rs.85,00,000, machinery Rs 50,00,000 and sundry liabilities Rs. 10,00,000 for a purchase consideration of Rs.1,00,00,000. Payment of Rs. 10,00,000 was made through a cheque and the remaining amount by issue of 11% Debentures of 100 each at a premium of 20%. Pass necessary journal entries for the above transactions in the books of Almond Ltd.
Section C
What are the options available to select ‘Minimum’ and ‘Maximum’ type while changing conditional format ?
The computer screen shows correct a #DIV/0! Error when a number is divided by zero in the calculations. Give the reason for showing this error (except the one given here). Also state the possible solutions to correct this error.
Calculate Revenue from Operations from the following information :
Average inventory — Rs. 1,20,000
Inventory turnover ratio — 8 times Goods are sold at a profit of 20% on revenue from operations
(ii) Calculate Trade Payables Turnover Ratio from the following information :
Credit purchases during 2024 — 25 : Rs 24,00,000
Creditors on 1st April, 2024 : Rs 3,00,000
Bills Payables on 1st April, 2024 : Rs 2,00,000
Creditors on 31st March, 2025 : Rs 4,80,000
Bills Payables on 31st March, 2025 : Rs. 2,20,000
From the details given below, calculate
(i) Quick Ratio
(i) Working Capital Turnover Ratio
Trade Receivables Rs.5,00,000
Inventory Rs. 2,40,000
Marketable Securities Rs.1,20,000
Cash 80,000
Prepaid Expenses Rs. 60,000
Bills Payable Rs. 1,20,000
Sundry Creditors Rs.2,40,000
Expenses Payable Rs.1,40,000
Debentures Rs.300000
Revenue from Operations Rs. 24,00,000
On 1st April, 2024, Smaran Ltd. issued 60,000, 11% Debentures of Rs. 100 at a premium of 10%, redeemable at par after five years. The company closed its books on 31st March every year. Pass necessary journal entries in the books of the company for issue of debentures, payment of interest on debentures and writing off interest for the year ended 31st March, 2025.
Anmol, Kapeesh and Meera were partners in a firm sharing profits and losses in the ratio of 4 : 3 : 3. The firm closes its books on 31st March every year. On 1th July, 2025, Kapeesh died. On that date his capital account showed a credit balance of Rs. 2,50,000 and he had withdrawn Rs 20,000 till that date for personal use. On the date of Kapeesh’s death, the firm had a General Reserve of Rs 90,000. The partnership deed provided that on the death of a partner, his executors will be entitled to the following :
(i) Balance in the capital account and interest on the same @ 12% p.a.
(ii) His share in the goodwill of the firm. The goodwill of the firm on Kapeesh’s death was valued at Rs 1,40,000.
(iii) His share in the profits of the firm was to be calculated on the basis of previous year’s profit. The profit of the firm for the year ended 31st March, 2025 was Rs. 6,00,000. Prepare Kapeesh’s Capital Account to be presented to his executors.
Section D
Using the Formula tab and dialog box, write the formula to create function ‘IF’ on the given spreadsheet, where the total income minus expenses is 20% if it is more than Rs. 50,000 and 10% if it is less than Rs.50,000. Also write the result statement.
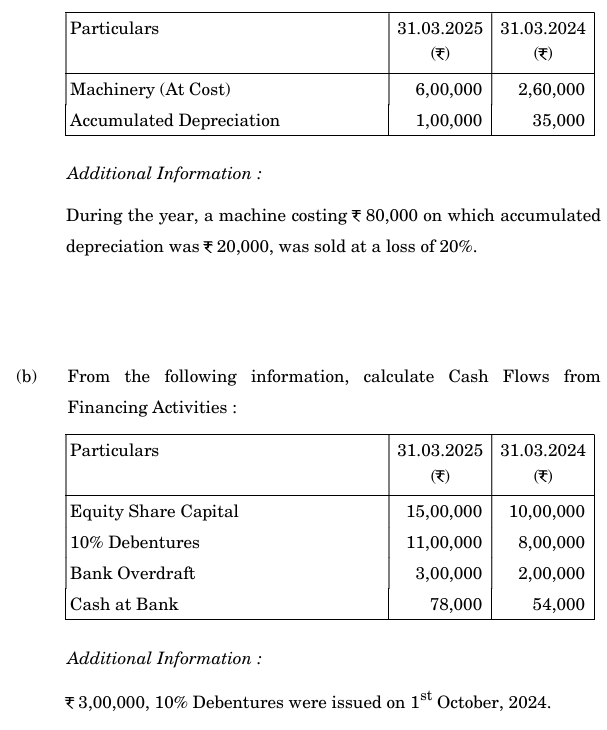
(a) From the following information, calculate Cash Flows from Investing Activities :
Bright Motors Ltd. was registered with an authorised capital of 10,00,00,000 divided into equity shares of Rs. 100 each. The company issued 3,00,000 shares to the public for subscription. The amount was payable as follows :
On application — Rs. 30 per share
On allotment — Rs.50 per share
On first and final call — balance
All the shares were fully subscribed. All amounts were duly received except from Raman, a holder of 500 shares, who failed to pay the first and final call.
(i) Total number of shares into which the authorised share capital of the company is divided, is :
(A) 10,00,00,000 (B) 1,00,00,000 (C) 10,00,000 (D) 3,00,000
(iI) Amount of ‘Subscribed and fully paid-up capital’ of Bright Motors Ltd. will be :
(A) Rs. 2,99,50,000 (B) Rs.3,00,00,000(C) Rs 10,00,00,000 (D) Rs2,99,90,000
(iii)Amount of ‘Subscribed but not fully paid-up capital’ of Bright Motors Ltd. will be
(A) 2,99,90000 (B) 29950000 (C) 30000000 (D) 40000:
(iv )Amount of ‘Share Capital’ to be presented in the Balance Sheet of Bright Motors Ltd. will be :
(A) 30000000 (B) 29950000(C) 29990000 (D) 100000000
(v)If the defaulting 500 shares are forfeited, Share Forfeiture Account’ will be shown in the ‘Notes to Accounts’ at : (A)Rs. 10000 (B) Rs.40000 (C) Rs. 50000(D) Rs. 5000
(vi) If all the forfeited shares are reissued @ Rs.90 per share fully paid-up, the amount credited to Capital Reserve Account will be :
(A) 35000 (B) 40000 (C) 10000 (D) 50000
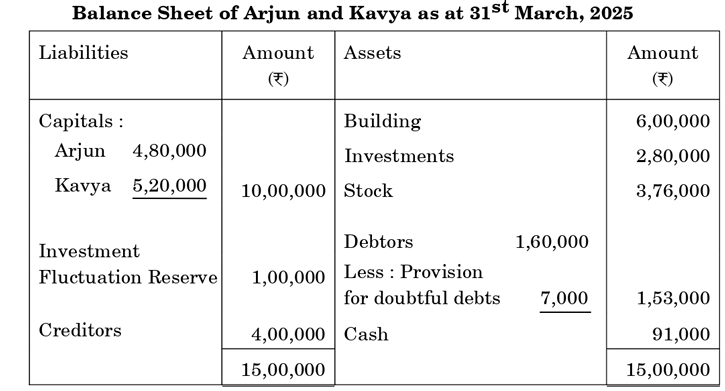
Arjun and Kavya were partners in a firm sharing profits and losses in the ratio of 3 : 2. Their Balance Sheet as at 31st March, 2025 was as follows :
On 1st April, 2025, Raghav was admitted as a new partner for 1/4th share in the profits of the firm on the following terms :
(i) Raghav shall bring Rs. 5,00,000 as his capital.
(ii) Goodwill of the firm was valued at Rs. 4,00,000. Raghav was unable to bring his share of goodwill premium in cash.
(iii )Provision for doubtful debts was to be created @ 10% on debtors.
(iv) Investments were valued at Rs.2,00,000 and building was to be brought down to Rs. 5,00,000.
(v)Capitals of Arjun and Kavya were to be adjusted on the basis of Raghav’s capital in the business. Actual cash was to be paid off or brought in by the old partners as the case may be. Prepare Revaluation Account and Partners’ Capital Accounts.
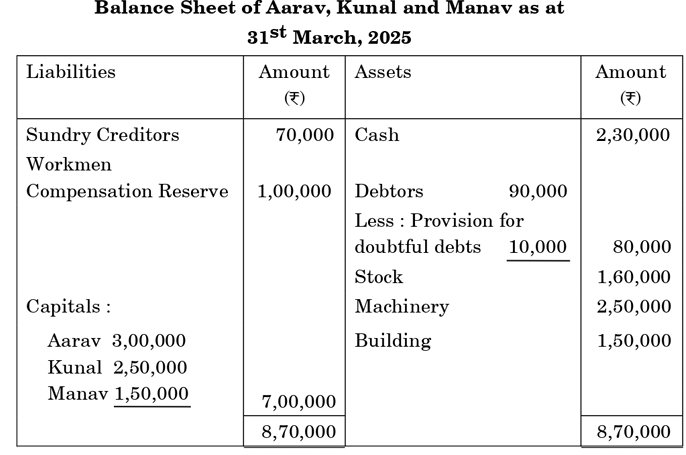
Aarav, Kunal and Manav were partners in a firm sharing profits and losses in the ratio of 5: 3 : 2. Their Balance Sheet as at 31st March, 2025 was as follows :
Aarav retired on the above date and it was agreed that :
(i) Kunal and Manav will share future profits in the ratio of 1:4.
(ii) Goodwill of the firm be valued at Rs 6,00,000 and the retiring partner’s share would be adjusted accounts of the remaining partners.
(iii) An unrecorded creditor of Rs. 20,000 was to be taken into account. (iv) Debtors of Rs. 15,000 were to be written off as bad debts.
(v) Liability on account of workmen compensation amounted to Rs. 40000
(vi) Amount account. payable to Aarav was transferred to his loan
Pass necessary journal entries for the above transactions in the books of the firm on Aarav’s retirement.
Astha Ltd. invited applications for issuing 1,00,000 equity shares of ₹ 10 each. The amount per share was payable as follows : ₹2 on application; ₹ 3 on allotment; ₹ 3 on first call and ₹ 2 on second and final call. Applications were received for 1,50,000 shares. Applications for 30,000 shares were rejected and application money refunded. The shares were allotted on pro-rata basis to the applicants of 1,20,000 shares. Excess towards sums money received with applications was adjusted due on allotment. All shareholders paid the allotment money except Sarthak, who was allotted 2,000 shares. These shares were forfeited. The first call was made thereafter and duly received. The second and final call was not yet made. of Astha Pass necessary journal entries for the above transactions in the books Ltd. Open Calls-in-Arrears Account, wherever required.
Orion Enterprises Ltd. invited applications for issue of 70,000 equity shares of ₹ 10 each at a premium of ₹ 1 per share. The amount was payable as follows :
On Application – ₹ 4 per share (including premium ₹ 1 per share)
On Allotment – ₹ 6 per share
On First and Final Call – Balance
Applications were received for 2,00,000 shares. Allotment was made as under :
Category A : Applicants for 1,20,000 shares were allotted 60,000 shares.
Category B : Applicants for 80,000 shares were allotted 10,000 shares.
Excess money received with applications was adjusted towards sums due on allotment only. Meeta, from category A, who was allotted 500 shares, failed to pay allotment money and first and final call and Japna, from category B, who had applied for 1,600 shares, failed to pay the first and final call money.
Pass necessary journal entries in the books of Orion Enterprises Ltd. for the above transactions.
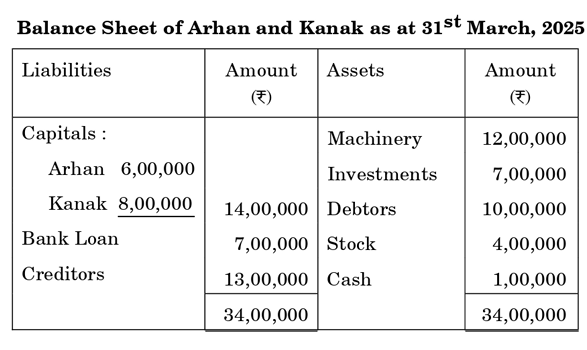
Arhan and Kanak were partners in a firm sharing profits and losses in the ratio of 3 : 2. Their Balance Sheet as at 31st March, 2025 was as follows :
The firm was dissolved on the above date and the following transactions took place :
(i) 50% of the creditors were given stock in full settlement of their dues. Remaining creditors were settled at 20% discount.
(ii) Investments were taken over by Kanak at ₹ 8,40,000.
(iii) Debtors realized ₹ 8,50,000 and machinery was sold at 70% of book value.
(iv) Realisation expenses amounted to ₹ 1,20,000 which were paid by Arhan.
Prepare Realisation Account.
Other Years — Accountancy