QUESTION PAPER
2026 BOARD EXAM
CBSE Class 12 Commerce Accountancy Board Paper 2026 — Set 2
2026
Accountancy
Class 12 Commerce
CBSE EXAMINATION PAPER-2026
ACCOUNTANCY
(Solved)
General Instructions :
Read the following instructions carefully and follow them :
- This question paper contains 57 questions. All questions are compulsory.
- This question paper is divided into 4 sections.
- Section A – questions number 1 to 33 are multiple choice questions
- Section B – questions number 34 to 44 are short answer
- Section C – questions number 45 to 49 are long answer type i
- Section D – questions number 50 to 57 are long answer type ii
- There is no overall choice given in the question paper. However, an internal choice has been provided in few questions.
- Use of calculator is NOT allowed.
Section A
Navya, Kartik and Samir were partners in a firm sharing profits and losses in the ratio of 4:3:1. Samir was given a guarantee that his share of profit in any year will not be less than ₹ 57,000. Any deficiency on this account was to be borne by Navya and Kartik equally. The firm earned a profit of ₹ 4,00,000 during the year ended 31st March, 2025. The amount of deficiency borne by Kartik was
Nandita and Prabha were partners in a firm manufacturing furniture. They were sharing profits and losses in the ratio of 8:7. During the year ended 31st March 2025, Nandita withdrew ₹ 80,000 in cash and ₹ 20,000 as furniture for her personal use. The partnership deed provided for charging interest on partner’s drawings @ 6% p.a. The amount of interest on Nandita’s drawings for the year ended 31st March 2025 was :
As per Companies Act 2013, the balance in Securities Premium Account cannot be utilized for :
When the company issues shares at a premium, the amount of premium can be received by the company along with :
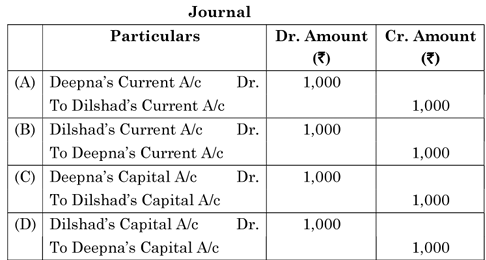
Dilshad, Ajit and Deepna were partners in a firm sharing profits and losses in the ratio of 2:2:1. Their fixed capitals were : ₹ 5,00,000, ₹ 4,00,000 and ₹ 1,00,000 respectively. After closing the accounts for the year ended 31st March 2025, it was discovered that interest on partners’ capitals was provided @ 6% p.a. instead of 7% p.a. The adjustment entry to rectify the above error will be :
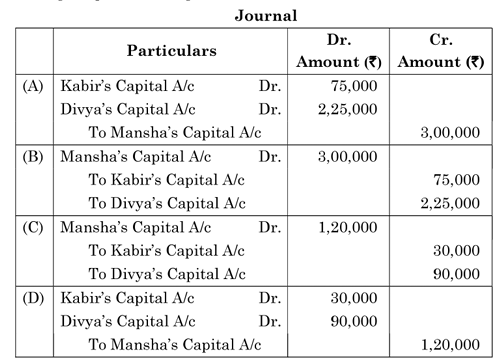
Kabir, Divya and Mansha were partners in a firm sharing profits and losses in the ratio of 5:4:1. With effect from 1st April 2025, they decided to share the future profits and losses in the ratio of 4:1:5. For this purpose, the goodwill of the firm was valued at ₹ 3,00,000. The necessary journal entry for the treatment of goodwill because of change in profit sharing ratio will be :
In case of dissolution of a partnership firm, the losses, including deficiencies of capital, shall be paid first :
Debentures which do not have a specific charge on the assets of the company are known are :
Zubin, Nidhi and Reena were partners in a firm sharing profits and losses in the ratio of 2:1:2. The firm closes its books on 31st March every year. On 31st July, 2025 Reena died. Her share in the profits of the firm from the last balance sheet till the date of death was to be calculated on the basis of previous year’s profit. The profit of the firm for the year ended 31st March, 2025 was ₹ 6,00,000. Reena’s share of profit till the date of her death was
On the dissolution of the partnership firm of Puneet and Binny, an unrecorded asset of ₹ 56,000 was given to an unrecorded creditor of ₹ 70,000 in settlement of his claim of ₹ 50,000 and the balance was paid to him in cash. Realisation Account will be_______ by______.
Shiv, Riya and Rohit were partners in a firm. On 1 st October, 2024 Rohit had given a loan of ₹ 2,00,000 to the firm, at an interest rate of 10% p.a. as per the partnership agreement. The accountant of the firm is emphasizing that interest on loan will be paid at 6% p.a. The amount of interest on loan paid to Rohit for the year ended 31st March, 2025 will be :
Sameer, Rajat and Aastha were partners in a firm sharing profits and losses in the ratio of 2:3:1. Rajat retired from the firm on 31st March, 2025. On the date of Rajat’s retirement, the Balance Sheet of the firm showed a balance of ₹ 2,40,000 in Workmen Compensation Fund. The claim on account of workmen compensation amounted to ₹ 1,80,000. The amount credited to Rajat’s capital account on the treatment of Workmen Compensation Fund would be
Meera, Varun and Tarun were partners in a firm sharing profits and losses in the ratio of 5:2:3. Meera retired and Varun and Tarun decided to share future profits and losses equally. On Meera’s retirement, the goodwill of the firm was valued at ₹ 5,00,000. The amount that was debited to Varun’s and Tarun’s capital account for the treatment of goodwill was
Amita, Shivani and Tarush were partners in a firm sharing profits and losses in the ratio of 4:3:2. Tarush’s share of profit at the end of the year amounted to ₹ 1,80,000. Amita’s share of profit at the end of the year was :
On 1st April, 2024 Vinar Ltd. issued ₹ 5,00,000, 9% debentures of ₹ 100 each at 10% discount. Interest is payable half yearly on 30th September and 31st March every year. The amount of interest written off on 31st March, 2025 was :
Bishan Ltd. acquired assets worth ₹ 12,60,000 and took over liabilities of ₹ 2,40,000 of Nimi Ltd. for a purchase consideration of ₹ 9,40,000. Bishan Ltd. issued 12% debentures of ₹ 100 each at a discount of 6% in favour of Nimi Ltd. for payment of purchase consideration. The number of debentures issued were
Vani, Vanya and Ajay were partners in a firm sharing profits and losses in the ratio of 5:3:2. Vani retired and her share was taken over by Vanya and Ajay in the ratio of 2:3. The new profit sharing ratio between Vanya and Ajay after Vani’s retirement was :
Devki and Neena were partners in a firm sharing profits and losses in the ratio of 4:3. Amar was admitted as a new partner for 1/5t share in the profits of the firm. Amar acquired 1/3 rd of his share from Devki. How much share did Amar acquire from Neena ?
Statement-I : Cash equivalents mean short term highly liquid investments that are readily convertible into known amounts of cash and which are subject to an insignificant risk of changes in value. Statement-II : An investment normally qualifies as a cash equivalent only when it has a short maturity period of three months or more from the date of acquisition. Choose the correct alternative from the following :
Which of the following transactions is NOT a cash flow from investing activity ?
Which of the following transactions will not result in flow of cash ?
In common size income statement, each item is expressed as a percentage of_______.
The statements which are useful both in intra firm comparison over different years and also in inter firm comparison for the same year or for several years are known as :
Which of the following is not a part of equity and liability group of accounts ?
Which chart element details the data values and categories below the chart :
Depreciation is generated from which of the following accounting sub- system :
Which type of software package is suitable for an organization where the volume of accounting transaction is very low and adaptability is very high ?
Section B
Bose and Roy were partners in a firm sharing profits and losses in the ratio of 2:1. Bose withdrew the following amounts from the firm for personal use during the year ending 31ˢᵗ March, 2025 :
(i) For the first three months, he withdrew ₹ 3,000 at the beginning of every month.
(ii) For the remaining months, he withdrew ₹ 4,000 at the end of every month. Interest on drawings was to be charged @ 6% p.a. The books of the firm are closed on 31ˢᵗMarch every year. Calculate interest on Bose’s drawings for the year ending 31ˢᵗ March, 2025.
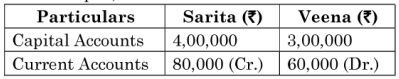
Sarita and Veena were partners in a firm sharing profits and losses in the ratio of 3:2. The balance in their capital and current accounts as on 1ˢᵗ April, 2024 were as under :
The partnership deed provided that Sarita was to be paid salary @ ₹ 2,000 per month whereas Veena was to get commission of ₹ 30,000 for the year. Interest on capital was to be allowed @ 8% p.a. The drawings of Sarita and Veena for the year ended 31ˢᵗ March, 2025 were ₹ 20,000 and ₹ 15,000 respectively. After preparing Profit and Loss Appropriation Account for the year ended 31ˢᵗ March, 2025, ₹ 36,000 and ₹ 24,000 were credited respectively to the current accounts of Sarita and Veena as their share of divisible profit. Prepare Current Accounts of Sarita and Veena.
Manya, Vivek and Vishal were partners in a firm sharing profits and losses in the ratio of 5:3:2. With effect from 1ˢᵗ April, 2025, they decided to share future profits and losses in the ratio of 3:5:2. Their Balance Sheet as at 31ˢᵗ March, 2025 showed the following balances :
(i) General Reserve ₹ 2,40,000.
(ii) Debit balance of ₹ 60,000 in Profit and Loss Account. Goodwill of the firm was valued at ₹ 6,00,000 and revaluation of assets and re-assessment of liabilities resulted in a gain of ₹ 2,00,000. Partners decided to distribute the amount of General Reserve and Profit and Loss Account. They also decided that revalued values of assets and liabilities were not to be recorded in the books.
Pass necessary journal entries to give effect to the above.
Miraya Ltd. took over assets of ₹ 70,00,000 and liabilities of ₹ 12,00,000 of Vishal Ltd. for a purchase consideration of ₹ 64,00,000. The payment of purchase consideration was made by issue of 50,000, 11% debentures of ₹ 100 each at a premium of 20% to Vishal Ltd. and the balance through a cheque.
Pass necessary journal entries for the above transactions in the books of Miraya Ltd.
Delta Ltd. invited applications for issuing 30,000, 9% debentures of ₹ 100 each at a premium of ₹ 30 per debenture. The full amount was payable on application. Applications were received for 40,000 debentures. Applications for 2,000 debentures were rejected and the application money was refunded. Debentures were allotted to the remaining applicants on pro rata basis. Pass the necessary journal entries for the above transactions in the books of Delta Ltd.
Average profits of a firm during the last few years were ₹ 1,60,000. The normal rate of return in a similar business is 10%. If the goodwill of the firm is ₹ 4,00,000 at four years purchase of super profit, find the capital employed by the firm.
A business earned average profits of ₹ 60,000 during the last three years. The normal rate of return on similar business is 12%. The value of net assets of the business is ₹ 4,00,000. Calculate the value of goodwill by :
(i) Capitalisation of average profits method.
(ii) Capitalisation of super profits method.
Classify the following items under the main heads and sub-heads (if any) of the Company’s Balance Sheet according to schedule III, part I of Companies Act, 2013 :
(i) Outstanding expenses
(ii) Work-in-progress
(iii) Capital Advances
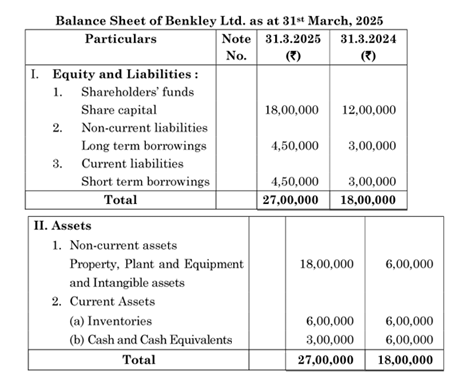
From the following balance sheet of Benkley Ltd., prepare a Comparative Balance Sheet
Explain any three features of Computerized Accounting System.
What is meant by cell reference, absolute cell reference and relative cell reference ?
Section C
Pass necessary journal entries in the books of Mitali Ltd. for issue of debentures in the following cases :
(i) Issued 7,000, 9% debentures of ₹ 100 each at a discount of 10%, redeemable at a premium of 5% after 5 years.
(ii) Issued 8,000, 11% debentures of ₹ 100 each at a premium of 10%, redeemable at a premium of 5% after 5 years.
Pass the necessary journal entries for the following transactions on the dissolution of the partnership firm of Arjun and Kunal after various assets (other than cash) and external liabilities have been transferred to Realisation Account :
(i) Arjun was appointed to look after dissolution work for which he was allowed a remuneration of ₹ 10,000. He agreed to bear the dissolution expenses. Actual dissolution expenses paid by Arjun were ₹ 9,500.
(ii) A creditor to whom the firm owed ₹ 9,000, accepted stock of ₹ 3,000 at a discount of 10% and the balance was paid to him in cash.
(iii) Kunal had given a loan of ₹ 20,000 to the firm. He was paid ₹ 19,000 in full settlement of his loan.
(iv) A piece of furniture, which was not recorded in the books was taken over by Arjun at ₹ 27,000 whereas its expected value was ₹ 30,000.
The following information has been obtained from the books of Naval Ltd. Trade receivables turnover ratio of the company is 4 times, cost of revenue from operations₹6,40,000 ; gross profit ratio 20%, closing trade receivables were ₹ 20,000 more than that in the beginning, cash revenue from operations being 33(1/3)% of credit revenue from operations. Calculate its opening and closing trade receivables.
What is Text Manipulation Function ? Explain its syntax.
Write the steps to change format of selected chart element.
Section D
Shanta Ltd. has an authorized capital of ₹ 30,00,000 divided into equity shares of ₹ 100 each. The company invited applications for issuing 28,000 shares. Applications for 27,000 shares were received and allotment was made to all the applicants in full. All calls were made and were duly received except on 300 shares on which the final call of ₹ 20 per share was not received. The company forfeited 200 of these shares on which final call was not received.
Answer the following questions :
(i) The nominal capital of the company is :
(A) ₹ 27,00,000 (B) ₹ 28,00,000 (C) ₹ 30,00,000 (D) ₹ 26,70,000
(ii) The issued capital of the company is :
(A) ₹ 27,00,000 (B) ₹ 28,00,000 (C) ₹ 30,00,000 (D) ₹ 26,70,000
(iii) Subscribed and fully paid-up capital of Shanta Ltd. is :
(A) ₹ 26,70,000 (B) ₹ 26,64,000 (C) ₹ 27,00,000 (D) ₹ 28,00,000
(iv) The amount of ‘share capital’ presented in the balance sheet of Shanta Ltd. will be :
(A) ₹ 28,00,000 (B) ₹ 26,70,000 (C) ₹ 27,00,000 (D) ₹ 26,94,000
(v) In the ‘Notes to Accounts’, the amount disclosed under ‘Share Forfeiture Account’ will be:
(A) ₹20,000 (B) ₹ 24,000 (C) ₹ 16,000 (D) ₹ 4,000
(vi) The amount of ‘calls in arrears’ disclosed in ‘Notes to Accounts’ will be :
(A) ₹ 2,000 (B) ₹ 10,000 (C) ₹ 8,000 (D) Nil
Anish, Bindu and Chandni were partners in a firm sharing profits and losses in the ratio of 2:2:1. Anish died on 31st December, 2023. After all necessary adjustments, Anish’s Capital Account showed a credit balance of ₹ 5,00,000. Anish’s executors were paid ₹ 1,00,000 in cash on 1st January, 2024 and the balance in two equal yearly instalments starting from 31st December, 2024 with interest @ 12% p.a. on the unpaid amount. The firm closes its books on 31st March every year. Prepare Anish’s Executors Account till the amount is finally paid.
(a) Pass necessary journal entries for forfeiture and reissue of forfeited shares in the following cases (i) Sanya Ltd. forfeited 2,000 shares of ₹ 10 each, issued at a premium of ₹ 2 per share, ₹ 8 called up, for non-payment of allotment money of ₹ 5 per share (including premium). Out of these, 700 shares were reissued to Dev as ₹ 8 paid up for ₹ 10 per share
(b) . (i) Moksh Ltd. forfeited 5,000 shares of ₹10 each on which first call of ₹ 3 per share was not received. The second and final call of ₹ 2 per share has not yet been called. Out of these, 2,000 shares were issued to Geeta as₹ 8 paid up for ₹ 7 per share.
Raga Ltd. invited applications for issuing 85,000 equity shares of ₹ 100 each at par. The amount was payable as follows :
On Application — ₹ 30 per share
On Allotment — ₹ 40 per share
On First and final call — balance
Applications were received for 80,000 shares and allotment was made to all the applicants in full. When the allotment was due, one shareholder failed to pay the amount on 300 shares held by him and another shareholder holding 500 shares paid the entire amount on his shares. The first and final call was duly received, along with arrears of allotment. Pass necessary journal entries for the above transactions in the books of Raga Ltd. Open ‘Calls in Arrears Account’ and ‘Calls in Advance Account’ wherever necessary.
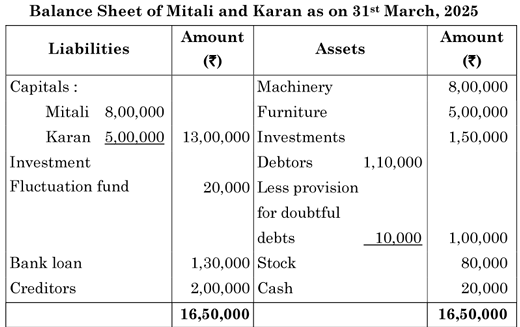
Mitali and Karan were partners in a firm sharing profits and losses in the ratio of 3:2. Their Balance Sheet as on 31st March, 2025 was as follows :
On 1st April, 2025, Nitin was admitted for 1/4 share in the profits of the firm on the following terms : (i) Nitin will bring ₹3,00,000 as Capital and ₹ 1,50,000 for his share of goodwill premium in cash.
(ii) Stock was sold at ₹ 70,000.
(iii) Machinery was found to be overvalued by ₹ 8,500.
(iv) All debtors were found to be good, hence provision for doubtful debts was not required.
(v) A liability of ₹ 3,500 included in creditors is not likely to arise.
(vi) The market value of the investments was ₹1,40,000.
(vii) The new profit sharing ratio between Mitali, Karan and Nitin will be 2:2:1. Pass necessary journal entries for the above transactions on Nitin’s admission.
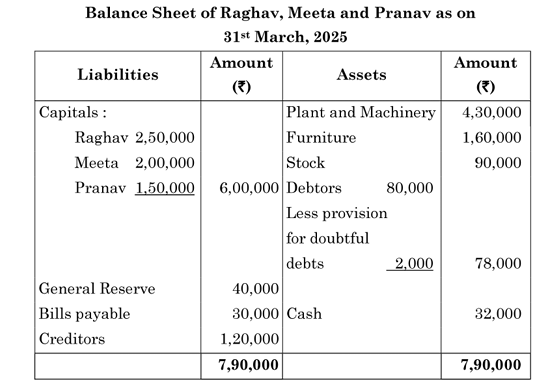
Raghav, Meeta and Pranav were partners in a firm sharing profits and losses in the ratio of 5:3:2. Their balance sheet as at 31st March, 2025 was as follows :
On 1st April, 2025, Pranav retired from the firm on the following terms
(ii) Plant and Machinery was found to be undervalued by ₹ 20,000.
(ii) Furniture was revalued at ₹1,62,000
(iii) The provision for doubtful debts on debtors was to be created @ 5%.
(iv) Goodwill of the firm was valued at ₹ 4,00,000 and the same was to be adjusted through the capital accounts of the remaining partners.
(v) Pranav was paid in cash brought in by Raghav and Meeta in such a way so as to make the capital proportionate to the new profit sharing ratio. Prepare Revaluation Account and Partners’ Capital Accounts.
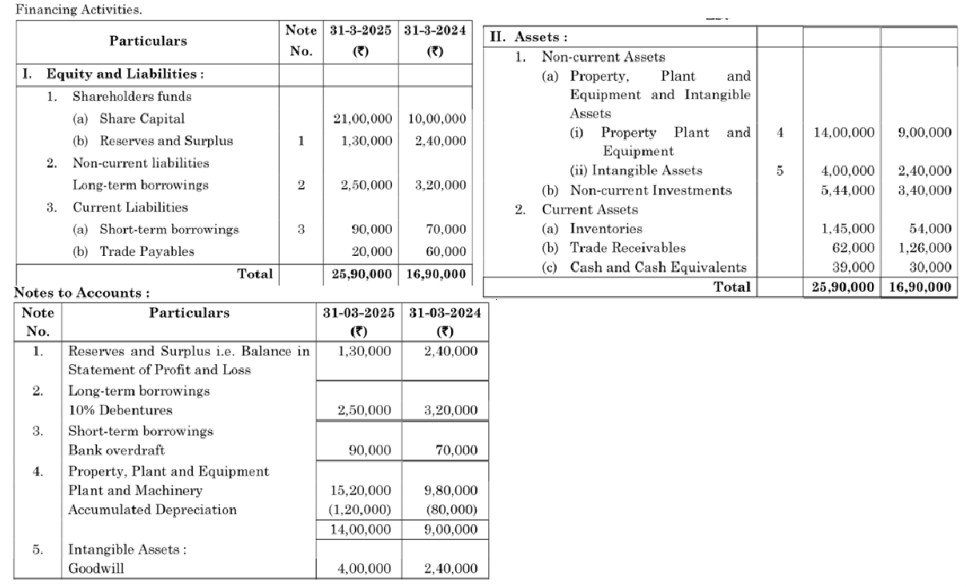
From the following Balance Sheet of Rama Ltd. as at 31st March, 2025, calculate cash flows from Investing Activities and cash flows from Financing Activities.
Additional Information :
(i) Depreciation amounting to ₹ 80,000 was charged on plant and machinery during the year.
(ii) During the year a new machine costing ₹ 8,00,000 was purchased and an old machine was sold at a profit of ₹ 8,000.
(iii) Interest paid on debentures amounted to₹ 32,000.
Name the error which will be displayed when a given number is divided by zero e.g. 25/0. State the reasons and the steps to be taken to correct this error.
Other Years — Accountancy