QUESTION PAPER
2026 BOARD EXAM
CBSE Class 12 Commerce Accountancy Board Paper 2026 — Set 3
2026
Accountancy
Class 12 Commerce
CBSE EXAMINATION PAPER-2026
ACCOUNTANCY
(Solved)
General Instructions :
Read the following instructions carefully and follow them :
- This question paper contains 57 questions. All questions are compulsory.
- This question paper is divided into 4 sections.
- Section A – questions number 1 to 33 are multiple choice questions
- Section B – questions number 34 to 43 are short answer
- Section C – questions number 44 to 49 are long answer type i
- Section D – questions number 50 to 57 are long answer type ii
- There is no overall choice given in the question paper. However, an internal choice has been provided in few questions.
- Use of calculator is NOT allowed.
Section A
Dharam and Karan were partners in a firm sharing profits and losses in the ratio of 7 : 3. On 1 st April, 2025, they admitted Vinod as a new partner in the firm. Dharam surrendered1/3rd Vinod and Karan surrendered 1/4th of his share in favour of his share in favour of Vinod. The new profit sharing ratio will be :
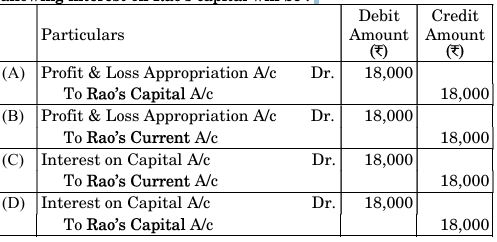
Damodar, Rao and Shridharan were partners in a firm sharing profits and losses in the ratio of 3 : 1 : 1. Their fixed capitals were ₹ 4,00,000; ₹ 3,00,000 and ₹ 2,00,000 respectively. Interest on capital is allowed at the rate of 6% per annum. Journal entry for allowing interest on Rao 's captial will be:
Rudali Ltd. invited applications for issuing ₹ 2,00,000 equity shares of ₹ 10 each at a premium of ₹ 2 per share. ₹ 5 per share (including premium) was payable on application. Applications for ₹ 2,60,000 shares were received. An applicant for ₹ 5,000 shares paid his entire share money along with application. The amount received on application was :
On 1st April, 2024, Mobi Ltd. issued 3,000, 9% Debentures of ₹ 1,000 each at a premium of 5%. The total amount of interest due on debentures for the year ended 31s t March, 2025 will be :
A company may reserve a portion of its uncalled capital to be called only in the event of winding up of the company. Such uncalled amount is called :
Anup, Bharti and Manoj were partners in a firm sharing profits and losses in the ratio of 11 : 8 : 1. From 1st April, 2025, they decided to share the future profits in the ratio of 2 : 2 : 1. The gain or sacrifice of each partner due to change in profit sharing ratio will be:
Divya and Bholi were partners in a firm sharing profits and losses in the ratio of 3 : 1. On 1st April, 2024, their fixed capitals were ₹ 8,00,000 and ₹ 6,00,000 respectively. On 30 th September, 2024, Bholi introduced ₹ 50,000 as additional capital. Partnership deed provided that interest on capital will be allowed @ 12% p.a. Interest on Bholi’s capital for the year ended 31st March, 2025 was
Persons who have entered into partnership with one another are collectively called :
In the absence of partnership deed, partners are entitled to :
When capitals of the partners are fluctuating, then the adjustments for drawings, interest on drawings, interest on capital, partners’ salary, etc. are shown in the________
Nigam Ltd. issued 40,000, 11% Debentures of 100 each at a certain rate of discount. The debentures were to be redeemed at 20% premium. Existing balance of Securities Premium before issue of these debentures was ₹ 13,00,000. After writing off ‘Loss on issue of debentures’, the balance in Securities Premium was ₹ 3,00,000. The above debentures were issued at a discount of :
Deep Ltd. issued 6,000, 9% Debentures of ₹ 500 each at ₹ 490 per debenture. 9% Debentures Account will be credited by :
Mogra Ltd. purchased assets of ₹ 14,40,000 from DK Ltd. It issued 9% Debentures of ₹ 100 each at a discount of 4% in full satisfaction of the purchase consideration. The number of debentures issued to DK Ltd. were
On 31st March, 2025, the partnership between Hari and Om was dissolved. Hari was appointed to look after dissolution work for which he was allowed a commission of ₹ 9,700. He agreed to bear the dissolution expenses. The actual expenses of dissolution amounted to ₹ 8,900 which were paid by Hari’s friend, Bhanu on his behalf. The amount debited to Realisation Account will be
Atul and Nisha were partners in a firm sharing profits and losses in the ratio of 4 : 1. Their capitals were ₹ 1,20,000 and ₹ 90,000 respectively. On 1st April, 2025, they admitted Mona as a new partner in the firm for 1/4 th share in the future profits. Mona brought ₹ 1,00,000 as her capital. The value of goodwill of the firm was :
Yashoda and Devi were partners in a firm sharing profits and losses in the ratio of 3 : 2. On 31st March, 2025, their balance sheet showed land and building at ₹ 20,00,000 and furniture at ₹ 6,00,000. On that date they admitted Poonam as a new partner for 1/4th share in the future profits of the firm. On Poonam’s admission, it was found that land and building is undervalued by 20%. On Poonam’s admission, Revaluation Account wil be;
Which of the following is a financial statement of a company ?
Which of the following is not a Solvency Ratio ?
The Current Ratio of Megh Raj Ltd. is 1; 5 : 1. Which of the following transactions will reduce the ratio ?
Which of the following are ‘investing activities’ for preparation of Cash Flow Statement ? Payment of taxes (ii) Payment of dividend and interest (iii Receipt of interest and dividend . Choose the correct option from the following
Which of the following statements is correct ?
Statement I :Operating activities are the activities that constitute the primary or main activities of an enterprise. Statement II : Cash advances and loans made by financial enterprises are usually classified as operating activities.
Identify what will be displayed on the screen when we specify an intersection of two areas that do not intersect.
Which financial function calculates the lump-sum amount for series of future payments ?
_________provides additional information about a data marker to identify the details of data point in a data series.
‘Computerised Accounting System enables changing the volume of data processing in accordance with the size and growth of the business.” Identify the feature of Computerised Accounting System being highlighted in the statement :
Section B
Tara, Meera and Neera were partners in a firm sharing profits and losses equally. Their capitals on 1st April, 2025 were ₹ 4,00,000; ₹ 3,00,000 and ₹ 2,00,000 respectively. The firm closes its books on 31st March every year. Tara died on 30th June, 2025. The partnership deed provides that in the event of death of a partner, her legal representatives will be entitled to the following
(i) Interest on capital @ 6% p.a.
(ii) Her share in the profits of the firm till the date of her death.
Tara had withdrawn ₹ 8,000 for her treatment till 30th June, 2025 and interest on drawings @ 12% p.a. is to be charged. Her share in the profits of the firm was to be calculated on the basis of last year’s profit. Last year’s profit amounted to ₹ 1,80,000. Prepare Tara’s Capital Account to be presented to her legal representatives on her death.
Laxmi, Rani and Priya were partners in a firm sharing profits and losses in the ratio of 5 : 7 : 8. Their fixed capitals were₹ 8,00,000; ₹ 7,00,000 and ₹ 5,00,000 respectively. The partnership deed provided interest on capital @ 9% per annum. For the year ending 31st March, 2025, interest on capital was provided @ 12% per annum. Showing your workings clearly, pass a single adjustment entry to rectify the error.
Sukesh and Surbhi were partners in a firm sharing profits and losses in the ratio of 5 : 3. On 1st April, 2024, they admitted Suman, as a new partner for 1/5th share in the profits of the firm with a minimum guaranteed profit of ₹ 1,20,000. Any deficiency arising on that account will be borne by Sukesh. The net profit of the firm for the year ended 31st March, 2025 was ₹ 5,50,000. Prepare Profit and Loss Appropriation Account of the firm for the year ended 31st March, 2025.
Oasis Ltd. purchased building worth₹ 12,00,000, machinery worth ₹1,90,000 and furniture worth ₹ 3,00,000 from Nitara Ltd. and took over its liabilities of ₹ 90,000 for a purchase consideration of ₹ 15,30,000. Oasis Ltd. paid the purchase consideration by issuing 11% Debentures of ₹100 each at a discount of 10%. Pass necessary journal entries in the books of Oasis Ltd. for the above transactions.
On 1st April, 2025, Bharat Heavy Industries Ltd. purchased the running business of Mac Ltd. consisting of sundry assets of the book value of ₹ 20,00,000 and sundry liabilities of ₹8,00,000 for a purchase consideration of ₹ 15,00,000. The purchase consideration was paid by issuing 8,000, 9% Debentures of ₹ 100 each at a premium of 25% and the balance was paid by a bank draft in favour of Mac Ltd. Pass necessary journal entries for the above transactions in the books of Bharat Heavy Industries Ltd.
Dhruv and Seema were partners in a firm sharing profits and losses in the ratio of 2 : 3. Their capitals were ₹ 18,00,000 and ₹ 12,00,000 respectively. The normal rate of return was 15%. The profits of the last four years were :
2021 - 22 ₹7,75,000
2022 - 23 ₹ 5,00,000
2023 - 24 ₹ (75,000)
2024 - 25 ₹ 7,00,000
The closing stock for the year 2024 — 25 was undervalued by ₹1,00,000. Goodwill of the firm is to be valued at three years’ purchase of last four years’ average super-profits. Calculate the value of goodwill of the firm.
Explain Sequential codes and Block codes with the help of example.
What are the three categories in which accounting entries can be classified while entering them in vouchers ?
Classify the following items under major heads and sub-heads (if any) in the Balance Sheet of a company as per Schedule-III, Part-I of the Companies Act, 2013 :
(i)Prepaid insurance
(ii)Securities Premium
(iii) Design
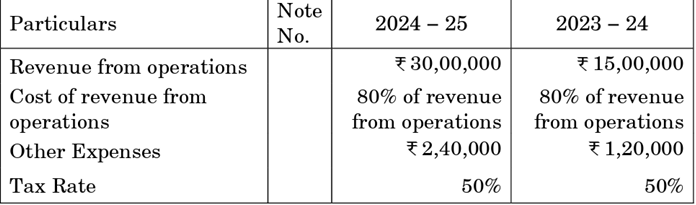
From the following information of Dholakia Ltd., prepare a Comparative Statement of Profit and Loss for the year ended 31st March, 2024 and 2025 :
Section C
Pass necessary journal entries for issue of debentures for the following transactions :
(i) AB Ltd. issued 30,000, 10% Debentures of ₹100 each at a premium of 5%, redeemable at a premium of 10%.
(ii) CD Ltd. issued 40,000, 8% Debentures of ₹ 100 each at par, redeemable at a premium of 10%.
Raman, Daman and Vikram were partners in a firm sharing profits and losses in the ratio of 5 : 4 : 1. On 31 March, 2025, their capitals were ₹ 6,00,000; ₹ 3,00,000 and ₹ 2,00,000 respectively. With effect from 1st April, 2025, they decided to share the future profits equally. Due to change in profit sharing ratio, it was agreed that :
(i) Goodwill of the firm will be valued at ₹3,00,000.
(iii)Revaluation of assets and liabilities will be carried out. The revaluation of assets and liabilities resulted in a loss of ₹ 12,000.
(iii)Total capital of the reconstituted firm will be ₹ 12,00,000 and will be in the new profit sharing ratio of the partners. For this purpose, necessary cash will be brought in by the partners or paid off to the partners, as the case may be.
Prepare Partners’ Capital Accounts on the reconstitution of the firm.
List the necessary information to be filled by a user on company creation screen.
What is a Chart/Graph ? Explain its advantages.
From the following information, calculate ‘Inventory Turnover Ratio’:
Revenue from operations ₹15,00,000
Opening inventory ₹2,00,000
Gross profit is 25% of cost of revenue from operations
. Closing inventory was 2 times the opening inventory.
From the following information, calculate ‘Interest Coverage Ratio’ :
Shareholders’ funds ₹ 30,00,000
8% Long-term debt ₹10,00,000
Net profit after tax ₹ 2,40,000
Tax Rate 40%
Section D
Madhav Ltd. invited applications for issuing 4,00,000 equity shares of ₹ 10 each at a premium of ₹ 4 per share. The amount was payable as follows :
On Application and Allotment —₹ 6 per share (including premium ₹ 2)
On First and Final Call — Balance Applications for 6,00,000 shares were received.
Applications for 1,00,000 shares were rejected and the application money was refunded. Shares were allotted on pro-rata basis to the remaining applicants. Excess money received on application and allotment was adjusted towards sums due on first and final call. A shareholder, who had applied for 500 shares, failed to pay the first and final call. His shares were forfeited. Pass necessary journal entries in the books of Madhav Ltd. for the above transactions.
(i) NN Ltd. forfeited 800 equity shares of ₹ 100 each for non-payment of the first call of ₹ 20 per share. The second and final call of ₹ 30 per share was not yet made. Out of the forfeited shares, 600 shares were re-issued for ₹ 54,000 as fully paid-up. Pass necessary journal entries for the above transactions in the books of NN Ltd.
(ii) KG Ltd. forfeited 7,000 equity shares of ₹ 100 each, issued at a premium of ₹ 20 per share, for non-payment of second and final call of ₹20 per share. The forfeited shares were re-issued at ₹ 80 per share, fully paid-up. Pass necessary journal entries for the above transactions in the books of KG Ltd.
Diksha Ltd. was registered with an authorised capital of ₹ 40,00,000 divided into shares of ₹ 10 each. On 1st April, 2025, the company offered to the public for subscription, 1,20,000 shares. Applications for 1,10,000 shares were received and allotment was made in full to all the applicants. A shareholder holding 10,000 shares failed to pay the second and final call of ₹ 2 per share. Answer the following questions on the basis of the above information :
(i) The amount of ‘calls in arrears’ will be :
(A) ₹10000
(B) ₹20000
(C) ₹80000
(D) ₹100000
(ii) The ‘subscribed and fully paid-up capital’ of Diksha Ltd. will be :
A) ₹9,80,000
(B)₹10,80,000
(C) ₹11,00,000
(D) ₹10,00,000
(iii)‘Subscribed but not fully paid-up capital’ of Diksha Ltd. will be :
A) ₹80,000
(B) ₹20000
(C) ₹10000
(D) Nil
(iv)The amount of ‘share capital’ to be shown in the balance sheet of Diksha Ltd. will be :
A) ₹11,00,000
(B) ₹10,80,000
(C) ₹10,00,000
(D) ₹9,80,000
(v) If all the shares on which second and final call was not received, are forfeited, ‘Share Forfeiture Account’ will appear in the ‘Notes to Accounts’ at :
A)₹20,000
(B) ₹80,000
(C) ₹100000
(D) ₹1,80,000
(vi)The minimum price at which the forfeited shares can be reissued is:
A)₹20,000
(B) ₹80,000
(C) ₹100000
(D) ₹1,10,000
Sophia and Lalit were partners in a firm sharing profits and losses equally. Their firm was dissolved on 31st March, 2025. After transferring sundry assets (other than cash in hand and cash at bank) and the third party liabilities to the Realisation Account, the following transactions took place :
(i) The firm had stock of the book value of ₹ 80,000. 50% of the stock was taken over by Sophia at 10% less than its book value and the remaining stock was sold at a gain of 15%.
(ii) There was an unrecorded investment which was sold for ₹ 25,000.
(iii) There were debtors of ₹1,20,000. Debtors realised 90% only and ₹ 5,000 were recovered for bad debts written off last year.
(iv) Sophia had given a loan to the firm of₹ 52,000. She was paid ₹ 41,000 in full settlement of her claim.
(v) Creditors of ₹ 60,000 were paid at a discount of 5%.
(vi) Expenses of realisation amounting to ₹ 7,000 were paid by Lalit.
Pass necessary journal entries for the above transactions in the books of
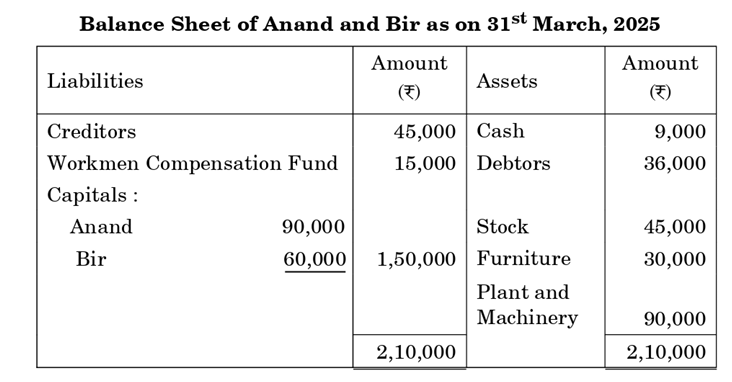
(a) Anand and Bir were partners in a firm sharing profits and losses in the ratio of 3 : 2. On 31st March, 2025, their Balance Sheet was as follows :
On 1st April, 2025, they admitted Vishal as a new partner for 1/6 th share in the profits of the firm. It was agreed that :
(i) Vishal will bring ₹45,000 as his capital and ₹ 15,000 for his share of goodwill premium
(ii) Stock was to be reduced by 10% and machinery was to be appreciated by 10%.
(iii) Furniture was revalued at ₹ 27,000
(iv) 5% provision for bad debts was to be created and ₹ 600 were to be provided for outstanding repair bill.
(v) There were unrecorded investments of ₹ 3,000 which were to be recorded.
(vi) A creditor of ₹ 900 was not likely to claim his money and hence was to be written off. Pass necessary journal entries for the above transactions in the books of the firm on Vishal’s admission..
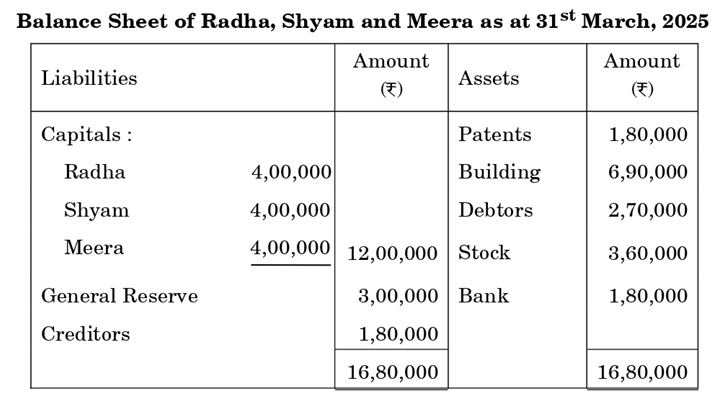
Radha, Shyam and Meera were partners in a firm sharing profits and losses equally. Their Balance Sheet as at 31st March, 2025 was as follows :
Shyam retired from the firm on the above date on the following terms :
(i) The new profit sharing ratio between the remaining partners was agreed at 3 : 2.
(ii) The value of stock was to be reduced by ₹ 1,20,000.
(iii) Patents were considered as valueless and hence were to be written off.
(iv) Goodwill of the firm was valued at ₹ 6,00,000 on Shyam’s retirement.
(v) Shyam was paid ₹ 1,00,000 immediately on his retirement and the balance was transferred to his loan account.
Prepare Revaluation Account and Partners’ Capital Accounts.
A user wishes to change a ‘Text Option’ as an element of chart. State how can this be done.
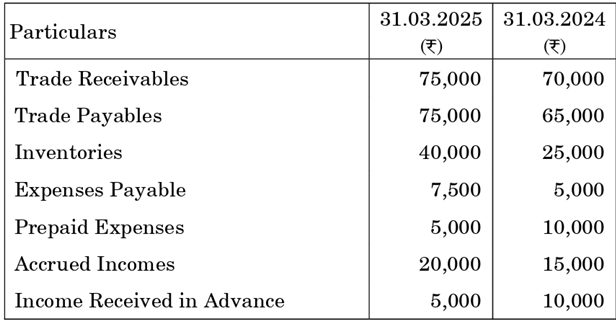
JC Ltd. earned a net profit of ₹ 50,000 after providing depreciation of ₹ 20,000 on fixed assets and a transfer of ₹ 15,000 to general reserve. The position of its Current Assets and Current Liabilities was as follows :Calculate cash flows from operating activities.
Other Years — Accountancy