QUESTION PAPER
2026 BOARD EXAM
CBSE Class 12 Commerce Accountancy Board Paper 2026 — Set 1
2026
Accountancy
Class 12 Commerce
CBSE EXAMINATION PAPER-2026
ACCOUNTANCY
(Solved)
General Instructions :
Read the following instructions carefully and follow them :
- This question paper contains 57 questions. All questions are compulsory.
- This question paper is divided into 4 sections.
- Section A – questions number 1 to 33 are multiple choice questions
- Section B – questions number 34 to 43 are short answer
- Section C – questions number 44 to 49 are long answer type i
- Section D – questions number 50 to 57 are long answer type ii
- There is no overall choice given in the question paper. However, an internal choice has been provided in few questions.
- Use of calculator is NOT allowed.
Section A
The books of Mehul and Barkha showed that their capital employed on 31st March, 2025 was ₹ 6,00,000. If the normal profits are ₹ 60,000 and super profits are₹ 20,000, then the normal rate of return is :
T.D. Ltd. issued ₹ 10,00,000, 9% debentures at a discount of 10% redeemable at a certain rate of premium. On issue of these 9% debentures, the premium on redemption of debentures account was credited by ₹ 1,00,000. The amount of ‘loss on issue of debentures’ was :
Tarun and Tej were partners in a firm sharing profits and losses in the ratio of 3 : 2. On 1st April 2024, Tej had given a loan of ₹ 50,000 to the firm. The net profit of the firm before charging interest on loan was ₹ 3,75,000. The firm closes its books on 31 st March every year. The amount of profit transferred from Profit and Loss Account to Profit and Loss Appropriation Account will be
Ashok and Vasu were partners in a firm sharing profits and losses in the ratio of 4 : 3. Their capitals on 31st March, 2025 were ₹ 3,00,000 and ₹ 3,75,000 respectively. During the year ended 31st March, 2025 Vasu withdrew ₹ 40,000 for his personal use and introduced ₹1,50,000 as additional capital in the business. Profit of the firm for the year ended 31st March, 2025 was ₹ 1,40,000. Vasu’s capital in the beginning of the year was :
Soni and Kush were partners in a firm sharing profits and losses in the ratio of 4 : 5. Hitesh was admitted as a new partner for 1/5th share in the profits of the firm. After all adjustments regarding general reserve, goodwill, and gain on revaluation of assets and reassessment of liabilities, the balances in capital accounts of Soni and Kush were₹ 7,00,000 and ₹ 13,00,000 respectively. Hitesh brought in proportionate capital for his 1/5th share in the profits of the firm. The amount of proportionate capital brought in by Hitesh was
‘A company is formed according to the provisions of Company Law’ indicates which of the following characteristics of a company ?
Chandan, Ravi and Mahesh were partners in a firm sharing profits and losses in the ratio of 5 : 4 : 1. From 1st April, 2025 they decided to share the future profits in the ratio of 3 : 2 : 1. On that date there existed a general reserve of ₹ 7,00,000 in the books of the firm which they decided to distribute among themselves. In which ratio will the general reserve be distributed among the partners ?
Suman and Tanya were partners in a firm sharing profits and losses in the ratio of 2 : 1. With effect from 1st April, 2025, they decided to share the profits equally. On that date furniture was appearing in the books of the firm at ₹ 4,50,000. At the time of change in the profit sharing ratio, it was found to be undervalued by 10%. In the new balance sheet, furniture will be shown at :
Tula, Ram and Madhvi were partners in a firm. The partnership deed provided for interest on partners drawings @ 12% p.a. The firm closes its books on 31st March every year. Starting from 31st December, 2025 Madhvi withdrew ₹ 40,000 at the end of every month for her personal use. Interest on Madhvi’s drawings will be
Dharam, Karam and Raman were partners in a firm sharing profits and losses in the ratio of 7 : 8 : 5. On 31st March, 2025, Raman retired from the firm. Dharam and Karam decided to share profits in future in the ratio of 11 : 9. Their gaining ratio will be:
On 1st April, 2024, Dina Ltd. issued 8,000, 9% debentures of ₹ 100 each at a discount of 6%. The total amount of interest due on debentures for the year ended 31st March, 2025 will be :
Sakshi Ltd. forfeited 500 equity shares of ₹ 10 each, issued at a premium of ₹ 2 per share for non-payment of second and final call of ₹ 4 per share (including premium). The maximum amount of discount at which these shares can be reissued is :
Surya Ltd. issued 50,000 equity shares of ₹ 10 each. The amount was payable as follows : on Application - ₹ 3 per share on Allotment — ₹ 2 per share on First and Final Call — the balance Usha, to whom 700 shares were allotted, paid her entire share money on allotment. Raj, to whom 300 shares were allotted did not pay the first and final call. The amount to be debited to Bank Account for first and final call after it becomes due will be :
Chaman and Vatika were partners in a firm sharing profits and losses in the ratio of 4 : 5. They admitted Mohan as a new partner for 1/5th share in the profits of the firm. Mohan acquired his share equally from Chaman and Vatika. The new profit sharing ratio of Chaman, Vatika and Mohan will be :
Lalita, Shivani and Madhuri were partners in a firm sharing profits and losses in the ratio of 3 : 2 : 1. Madhuri retired from the firm on 31st March, 2025. The balance in her capital account on the date of her retirement was ₹ 1,80,000. Lalita and Shivani agreed to pay her ₹ 2,25,000 in full settlement of her claim. The goodwill of the firm on Madhuri’s retirement was
The encryption of data facilitates :
How many columns exist on Excel 2006 worksheet ?
‘Which of the following is not contained on formula tab on Excel ribbon ?
What will be displayed on the screen when Excel does not recognise the text or formula ?
What is the outcome of an arithmetic expression or function called ?
The process of identifying the financial strengths and weaknesses of the firm by properly establishing relationships between the various items of Balance Sheet and the Statement of Profit and Loss is called
Ratios calculated to measure the ability of the business to pay the amount due to stakeholders as and when it is due are known as
Which of the following transaction will affect the ‘Gross Profit Ratio’ of a company (i)Revenue from operations ₹ 1,00,000 (ii) Purchased goods worth ₹ 70,000. (iii) Goods costing ₹15,000 withdrawn for personal use. (iv) Goods costing ₹ 50,000 sold for ₹ 60,000.
Purchase of marketable securities or short term investments are not considered for the preparation of cash flow statement because :
Statement-1I : In case of non-financial enterprises, receipts of interest and dividend are classified as financing activities. Statement - II : In case of financial enterprises receipts of interest and dividend are classified as investing activities.
Section B
Average profit of a firm during the last few years is ₹ 8,00,000. In similar business, the normal rate of return is 10% of the capital employed. Assets of the business were ₹ 60,00,000 and its external liabilities were ₹ 20,00,000. Calculate the value of goodwill by:
(i) Capitalisation of super profits method
(ii) Super profit method if the goodwill is valued at four years’ purchase of super profits.
Sultan, Singh and Tulsi were partners in a firm sharing profits and losses in the ratio of 9 : 7 : 4. Their fixed capitals were ₹ 6,00,000, ₹ 5,00,000 and ₹ 4,00,000. The partnership deed provided that interest on partners capital accounts will be allowed at 10% per annum. After the final accounts for the year were prepared, it was found that interest on capital was allowed @ 12% per annum.
Pass the necessary adjusting journal entry.
Sameer and Manveer were partners in a firm sharing profits and losses in the ratio of 5 : 3. On 1ˢᵗ April, 2024, they admitted Sandeep as a new partner for 1/5ᵗʰ share in the profits with a guaranteed minimum amount of ₹ 80,000. Sameer and Manveer continue to share profits as before but agreed to bear any deficiency on account of guarantee to Sandeep in the ratio of 3 : 5. The net profit of the firm for the year ended 31ˢᵗ March, 2025 was ₹ 3,20,000. Prepare Profit and Loss Appropriation Account of Sameer, Manveer and Sandeep for the year ended 31ˢᵗ March, 2025.
Raunak Cotton Ltd. purchased machinery of ₹ 6,80,000 from Heavy Machines Ltd. The Payment to Heavy Machines Ltd. was made by issuing 10,500 equity shares of ₹ 50 each at a premium of 20% and the balance through a cheque.
Pass necessary journal entries for the above transactions in the books of Raunak Cotton Ltd.
Neo Ltd. took over assets of ₹ 25,00,000 and liabilities of ₹ 12,00,000 of Madura Ltd. for a purchase consideration of ₹ 18,00,000. Neo Ltd. issued 11% debentures of ₹ 100 each at a discount of 10% in full satisfaction of the purchase consideration.
Pass necessary journal entries for the above transactions in the books of Neo Ltd.
Shree and Hari were partners in a firm sharing profits and losses in the ratio of 2 : 3. Their fixed capitals were ₹ 4,00,000 and ₹ 3,00,000 respectively. The partnership deed provided that Hari is to be allowed a commission of 5% of net profit. The net profit of the firm for the year ended 31ˢᵗ March, 2025 was ₹ 1,00,000.
Pass the following journal entries in the books of the firm :
(i) For crediting Hari’s commission to his current account.
(ii) For transferring the commission to Profit and Loss Appropriation Account.
Classify the following items under major heads and sub-heads (if any) in the Balance Sheet of the company as per Schedule-III, Part-I of the Companies Act, 2013 :
(i) Stores and Spare parts
(ii) Livestock
(iii) Public Deposits
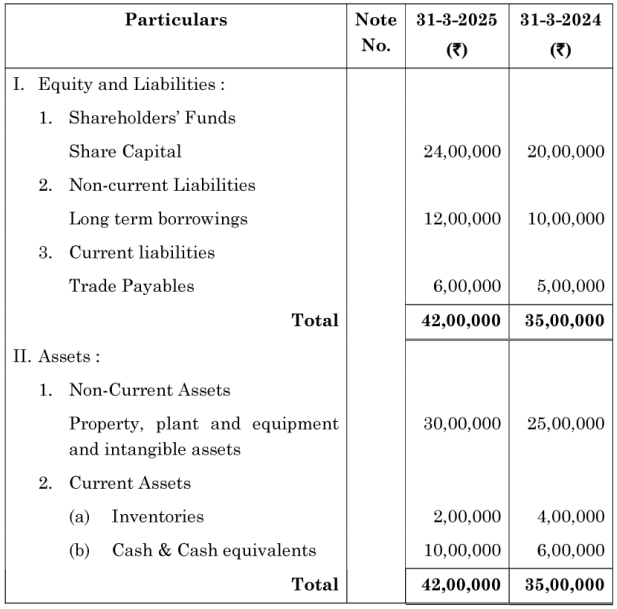
From the following Balance sheets of Royal Sugar Mills Ltd. as at 31ˢᵗ March, 2024 and 2025, prepare a Comparative Balance Sheet :
What are ‘Radar Charts’ ? What purpose do they serve ?
State any three advantages and three limitations of Computerised Accounting System.
Section C
On 1ˢᵗ April, 2024 Bhumika Ltd. issued 500, 9% debentures of ₹ 500 each at a discount of 10% redeemable at a premium of 6% after five years. On 31ˢᵗ March, 2025 the company had a balance of ₹ 30,000 in its Securities Premium Account.
Pass necessary journal entries for issue of 9% Debentures and writing off Loss on issue of Debentures. Also prepare ‘Loss on Issue of Debentures Account’.
Kiran, Raveena and Hina were partners in a firm sharing profits and losses in the ratio of 5: 3 : 2. The firm closes its books on 31ˢᵗ March every year. As per the terms of the partnership deed, on the death of any partner, the goodwill of the firm will be calculated on the basis of four times the average profits of the last three years. Hina died on 1ˢᵗ July 2025. The Profits for the last three years were :
2022-23 ₹4,75,000
2023-24 ₹4,05,000
2024-25 ₹3,20,000
Hina’s share of profit upto the date of death was to be calculated on the basis of previous year’s profit.
(i) Calculate goodwill of the firm and Hina’s share of goodwill.
(ii) Calculate Hina’s share in the profits of the firm till the date of her death.
(iii) Pass necessary journal entries for the treatment of goodwill without opening goodwill account and for Hina’s share of profit at the time of her death.
From the following information, calculate :
(i) Current ratio and
(ii) Debt to capital employed ratio
Information ₹
Total Assets 6,00,000
Non-Current Liabilities 1,40,000
Shareholders’ Funds 4,20,000
Non-current Assets 5,20,000
From the following information, calculate :
(i) Debt-Equity Ratio and
(ii) Total Assets to Debt ratio
Information ₹
Long-term borrowings 8,00,000
Other long-term liabilities 80,000
Long term provisions 1,20,000
Share capital 24,00,000
Reserves and Surplus 6,00,000
Non-current Assets 36,00,000
Current Assets 14,00,000
Current Liabilities 10,00,000
Name the table which is an interactive way to quickly summaries large amounts of data. State any three reasons why this table is designed.
Explain any two ways in which Computerized Accounting System safeguards the secrecy of business data.
Section D
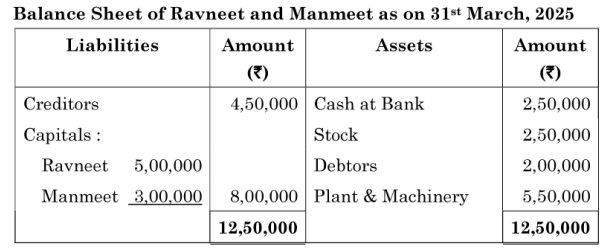
Ravneet and Manmeet were partners in a firm sharing profits and losses in the ratio of 7 : 3. On 31ˢᵗ March, 2025, their Balance Sheet was as follows :
On the above date, the firm was dissolved. The plant and machinery was sold at ₹ 4,87,000 and stock at 20% less than the book value. Debtors realised ₹ 1,40,000.
Ravneet agreed to bear all realisation expenses for which he was allowed a commission of ₹ 9,000. Actual realisation expenses amounted to ₹ 7,500. Prepare Realisation Account and Partners’ Capital Accounts.
Generic Pharma Ltd. invited applications for using 3,00,000 equity shares of ₹ 10 each at a premium of ₹ 6 per share. The amount was payable as follows :
on Application and Allotment — ₹ 4 per share (including premium of ₹ 2 per share)
on First and Final Call — Balance
Applications for 4,00,000 shares were received. Applications for 40,000 shares were rejected and the application money was refunded. Shares were allotted on pro-rata basis to the remaining applicants. Excess money received on applications was adjusted towards sums due on first and final call. Jain, an applicant for 3,600 shares failed to pay the first and final call. His shares were forfeited.
Pass necessary journal entries in the books of Generic Pharma Ltd. for the above transactions. Open ‘calls in arrears account’ and ‘calls in advance account’, wherever necessary.
Pass necessary journal entries for forfeiture and reissue of forfeited shares in the following cases :
(i) Diksha Ltd. forfeited 3,000 shares of ₹ 10 each for non-payment of final call of
₹ 2 per share. Out of these, 600 shares were reissued as fully paid up in such a way that ₹ 4,200 was transferred to capital reserve.
(ii) Ashoka Ltd. forfeited 2,000 equity shares of ₹ 100 each issued at a premium of 10% for non-payment of allotment money of ₹ 60 per share (including premium). The first and final call of ₹ 20 per share was not yet made. The forfeited shares were re-issued at ₹ 70 per share fully paid up.
Sanjay and Vijay were partners in a firm sharing profits and losses in the ratio of 4 : 3. On 1ˢᵗ April, 2025 they admitted Babul as a new 2/5ᵗʰ partner for 5 share in the profits of the firm. On Babul’s admission, the following was agreed upon :
(i) The new profit sharing ratio of Sanjay, Vijay and Babul will be 3:3:4.
(ii) The goodwill of the firm will be valued at four years purchase of the average profits of the last three years. The profits of the previous three years were :
Years Profit (₹)
2022-23 16,500
2023-24 17,500
2024-25 18,500
(iii) Babul will bring his share of goodwill premium in cash, half of which will be withdrawn by Sanjay and Vijay.
(iv) On Babul’s admission, revaluation of assets and reassessment of liabilities resulted in a loss of ₹70,000.
(v) At the time of Babul's admission, the firm had a General Reserve of ₹ 28,000.
(vi) After making necessary adjustments relating to goodwill, loss on revaluation and general reserve, the capital accounts of Sanjay and Vijay showed balances of ₹ 3,50,000 and ₹ 2,50,000 respectively. Babul brought proportionate capital for his 2/5ᵗʰ share in the profits of the firm.
Showing your workings clearly pass necessary journal entries for the above transactions in the books of the firm on Babul’s admission.
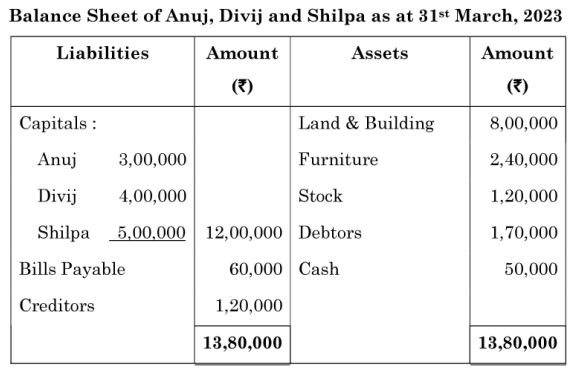
Anuj, Divij and Shilpa were partners in a firm sharing profits and losses in the ratio of 2 : 1 : 2. Their Balance Sheet as at 31ˢᵗ March, 2023 was as follows :
Anuj retired on the above date on the following terms :
(i) Anuj’s share of goodwill was valued at ₹ 90,000 and the same was to be treated without opening goodwill account.
(ii) Revaluation of assets and reassessment of liabilities resulted in a gain of ₹25,000.
(iii) Amount due to Anuj was transferred to his loan account, to be paid in two equal yearly instalments plus interest @ 12% p.a. on the unpaid balance starting from 31ˢᵗ March, 2024.
Prepare Partners’ Capital Accounts and Anuj’s Loan Account till it is fully discharged.
For the year ended 31ˢᵗ March 2025, Sona Ltd. made a profit of ₹ 4,00,000 after charging depreciation of ₹ 75,000 on fixed assets and a transfer of ₹ 1,50,000 to general reserve. Goodwill written off during the year was ₹ 80,000. The company sold machinery of the book value of ₹ 90,000 at ₹ 95,000. During the year, trade receivables increased by ₹ 40,000 and trade payables increased by ₹ 30,000. Prepaid expenses increased by ₹ 2,000 and outstanding wages decreased by ₹ 20,000. Calculate cash flows from operating activities.
Explain various options available to change the alignment of the text in the cells.
Dharma Ltd. was registered with an authorised capital of ₹ 30,00,000 divided into 3,00,000 equity shares of ₹ 10 each. The amount was payable as follows :
On Application — ₹ 2 per share
On Allotment — ₹ 5 per share
On First and Final Call — Balance
The company offered 90,000 shares for public subscription. All the shares were subscribed and the company received all the money due, except allotment and call money on 4,000 shares held by Aditi and call money on 3,000 shares held by Rohit. The directors forfeited shares of Aditi and Rohit.
Answer the following questions on the basis of above information :
(1) The nominal capital of Dharma Ltd. is :
(A) ₹ 30,00,000 (B) ₹ 3,00,000 (C) ₹ 9,00,000 (D) ₹ 33,00,000
(ii) The issued capital of the company is :
(A) ₹3,00,000 (B) ₹ 30,00,000 (C) ₹ 9,00,000 (D) ₹ 33,00,000
(iii) Subscribed and fully paid capital of Dharma Ltd. will be :
(A) ₹ 9,00,000 (B) ₹ 8,30,000 (C) ₹ 8,56,000 (D) Nil
(iv) The amount of ‘Share Capital’ presented in the Balance sheet of Dharma Ltd. under ‘Shareholders Funds’ will be :
(A) ₹ 8,30,000 (B) ₹ 8,59,000 (C) ₹ 9,00,000 (D) ₹ 30,00,000
(v) In the Notes to Accounts, the amount to be shown under ‘Share Forfeiture Account’ will be :
(A) ₹ 32,000 B) ₹ 12,000 (C) ₹ 44,000 (D) ₹ 29,000
(vi) Subscribed and not fully paid capital of Dharma Ltd. will be :
(A) ₹ 9,00,000 (B) ₹ 8,30,000 (C) ₹ 8,56,000 (D) Nil
Other Years — Accountancy